For banks, credit unions and lenders
Mortgage marketing that makes the shortlist first.
Borrowers compare lenders before the first application. Your site, search, AI answers and ads make you the trusted name they find, inside the lending rules.
- More applicants from every channel
- Every call and form tracked
- No setup fee
HOW TRUST BUILDS
Trust grows with every touchpoint
Where do prospects lose trust in you? Tap a step.
- Client
On its way.
A strategist will look at what you picked and email you. Check your inbox for the confirmation.
Want it sooner? Book a callWe build every touchpoint, in order.
WHAT WE HEAR FROM ADVISORS
Six things standing between you and the right clients.
Long decisions, strict rules and crowded sameness. Here is what advisory firms tell us, and what we do about each one.
- “
Compliance review slows everything down.
Every rate post, banner and blog goes back and forth with compliance for weeks. By the time it is approved, the rate has moved and the moment has passed.
HOW WE FIX IT
Copy built from approved templates, with trigger terms, APR, APY and Equal Housing notices placed correctly before compliance sees it. Your compliance officer keeps the final word.
Copywriting and Growth Manager - “
Borrowers find the big lenders and apps first.
National lenders and online apps own the search results. Our members and customers do not even know we offer mortgages or business loans until they have already applied somewhere else.
HOW WE FIX IT
Pages for each loan need and each place you serve, plus visibility in AI answers, so you are on the list when the trigger arrives.
SEO and AI search - “
Our loan officers market themselves, inconsistently.
Every loan officer has a different bio, a different photo and sometimes no NMLS ID. Some have their own sites. None of it matches the main website.
HOW WE FIX IT
One consistent loan officer page template with NMLS IDs, licenses, loan types and a booking link, matched across profiles and signatures.
Website and branding - “
Rate ads bring rate shoppers who never close.
We pay for clicks from people who compare twenty quotes and leave. The borrowers who would value our service never see an ad that speaks to them.
HOW WE FIX IT
Campaigns built on specific loan needs and allowed geographies, landing pages that explain your service, and reporting on funded loans, not clicks.
Paid ads and conversion - “
The website was built for depositors, not borrowers.
The homepage is a login box and a rate table. Loan pages are thin, the application start is hard to find, and the FDIC digital sign deadline is coming.
HOW WE FIX IT
A site that leads with the loan needs you want to grow, carries the required signs and notices, and makes the first step easy on a phone.
Website redesign - “
Agents send business, but co-marketing makes us nervous.
Realtors and builders want flyers, events and shared ads. Nobody is sure what RESPA allows, so the program either stalls or runs on hope.
HOW WE FIX IT
Co-marketing material and partner pages scoped with your counsel, so every shared piece is reviewed before it goes out.
Copywriting and Growth Manager - “
Nobody owns the marketing.
Marketing sits between retail, lending and compliance. The agency changes contacts, and no one is accountable for applications or funded loans.
HOW WE FIX IT
A named growth manager and a project manager, accountable for the plan and for clearing the review queue.
Growth Manager
FROM STRANGER TO CLIENT
Earn trust at every step of a long decision.
People rarely hire an advisor after one visit. They move through five stages, and your marketing has to meet them at each one.
- 1
Trigger
THEY THINK
“We found a house, or the business needs cash. Who do I even ask?”
THEY NEED
A page for their exact need that shows up in search and AI answers, and a brand they half remember.
SEO and AI search - 2
Check you out
THEY THINK
“Is this lender real, licensed or insured, and would they lend to someone like me?”
THEY NEED
NMLS IDs, insured status, Equal Housing notices, named loan officers and recent reviews.
Website and copywriting - 3
Compare
THEY THINK
“Are their numbers honest, and is the service better than the big lender’s app?”
THEY NEED
Dated rates with full disclosures, a plain explanation of the process and a clear reason to choose a local lender.
Branding and content - 4
Apply
THEY THINK
“How long will this take, and is it safe to share my documents?”
THEY NEED
A short first step on a phone, a secure application and a fast human reply.
Conversion - 5
Fund and stay
THEY THINK
“Did they do what they said, and should I keep banking here?”
THEY NEED
Consistency between the ad, the disclosures and the closing, then a reason to open the next account.
Growth Manager
YOUR GROWTH MANAGER
Your institution gets a growth manager who understands lenders.
A growth manager is the person accountable for growing your lending and deposits online. Yours is briefed on how borrowers choose: the short shopping window, existing relationships, referral partners, rate cycles and the disclosure rules behind every ad. They work alongside your compliance team, not around it, and they are your number one contact next to your project manager or specialist.
- STEP 1
Set goals
Agree what a good year looks like: the loan types, deposits and markets you want to grow.
- STEP 2
Allocate
Decide where effort goes: search, website, content, ads or loan officer and partner material.
- STEP 3
Review
Look at the numbers that matter: application starts, funded loans and accounts opened.
- STEP 4
Rebalance
Shift effort to what is working, and stop what is not, as rates and demand move.
ALREADY KNOWS
What your growth manager brings on day one
- 01How borrowers choose a lender: relationship, reputation, a nearby office and a short online check
- 02Why most borrowers apply once, and what that means for the application start
- 03What Regulation Z trigger terms and Regulation DD yield rules require in an ad
- 04Where Equal Housing notices, NMLS IDs and FDIC or NCUA statements belong
- 05Why RESPA Section 8 shapes every co-marketing program with agents and builders
- 06Which credit ad targeting options Google blocks in the US and Canada
- 07How rate moves change demand between purchase, refinance and home equity
- 08When to say no to a channel that does not fit your institution yet
Owns the plan
Decides what to do next, and in what order, so you are never guessing where to spend.
Plans around compliance review
Builds the review time into every schedule, so campaigns land when they are meant to.
Reads the rate cycle
Shifts effort between purchase, refinance, home equity, business lending and deposits as rates and demand move.
Meets you every month
A monthly meeting to review applications, funded loans and accounts opened, and agree the priorities.
Brings in specialists
Recommends and coordinates our SEO, ads, website, copy and brand specialists when you need them.
The Growth Manager Advisor level gives direction and advice, not hands-on implementation. Many institutions start there and add services when they are ready. Established teams can keep a growth manager on its own.
WHAT WE DO FOR YOUR FIRM
Everything your firm needs to grow online.
9 services built around how people choose a lender, and the rules you work under. Start with your growth manager, or with any one service.
- Growth ManagerSTART HERE
- A named contact, alongside your project manager or specialist
- A monthly meeting, constant communication and clear recommendations
- Decides what to do next, and in what order, across all of our services
- Useful on its own, and stays with you as you add services
Someone whose job is making sure your institution’s growth online succeeds.
See the service - SEO
- A page for each loan need, such as first-time buyers, home equity, equipment or working capital
- Local visibility for each staffed branch, with profiles that match your signage and lobby hours
- Loan officer pages with NMLS IDs, licenses and the areas they serve
- Technical fixes so Google can crawl and understand every page
A project manager, constant communication and one report a month.
See the service - AI search
- We test the questions borrowers put to ChatGPT, Gemini and Google’s AI features
- Explainers on APR, pre-approval and home equity, written with the disclosures in place
- Consistent legal name, NMLS ID and insured status across your site and profiles
- A monthly check on whether you are named
A clear picture of how AI answers describe your institution, and a plan to improve it.
See the service - Website redesign
- FDIC digital sign or NCUA statement, Equal Housing notices and non-deposit notices where they belong
- Rate pages with dated APR or APY and the assumptions beside them
- A short first step that hands off to your secure application
- Fast, accessible, mobile-first pages
A new site, built on a plan, with a project manager from kickoff to launch.
See the service - Web tools and apps
- Payment and affordability calculators with the required disclosures built in
- Pre-qualification and appointment flows that route to the right loan officer
- Rate tables your team can update and date in one place
- Simple dashboards for application starts by source
Scoped on a call, built to your brief, handed over with documentation.
See the service - Paid ads
- Campaigns built on loan needs and allowed geographies, with no restricted demographic targeting
- Landing pages that carry the APR, terms and Equal Housing notice the ad requires
- Ad copy checked against Regulation Z and platform policy, with final sign-off staying with your compliance team
- Budget decisions based on cost per funded loan or opened account
Campaigns you can see inside, with clear reporting.
See the service - Conversion optimization
- Research into where borrowers drop off between the rate page and the application
- Tests on forms, calls to action and page layout
- A clear, honest description of what happens after someone applies
- Before-and-after results you can read
Fewer wasted visits and a clear record of what changed applications.
See the service - Copywriting
- Loan and deposit pages written in your borrowers’ words
- Loan officer bios and process pages that build trust
- Rate and payment copy with trigger-term disclosures in place
- Drafts reviewed by you and your compliance team before they go live
Copy written from your institution’s knowledge and reviewed by you.
See the service - Branding
- Positioning: who you lend to and why they are better off with you
- A visual identity that works across branches, apps, ads and loan officer profiles
- One consistent look for every loan officer and partner piece
A brand your whole institution can use, not just a logo file.
See the service
- “Webtec is fantastic and you should hire them.”
- “Extremely professional team-- very consultative on how to develop a modern web interface.”
- “We are a small non-profit but Webtec design has treated us like a fortune 500 Company.”
- “Great support and experience from these guys.”
- “I am so impressed with WebTec's work on my website redesign.”
- “Webtec has done a great job with my website!”
- “We couldn't be more pleased with the speed and quality that they were able to deliver.”
- “Working with this team has been incredible!”
- “Webtec has been great to work with.”
- “From the minute we started with this group they have been excellent.”
- “We partnered with Webtec to design our new iMesh360 website, and the results exceeded expectations.”
MARKETING WITHIN THE RULES
Say it with confidence, within the rules.
Most advisory firms publish too little because the rules feel risky. Here is how we turn risky wording into copy that still sells.
Mortgage rates as low as 5.99%!5.99% APR on a 30-year fixed loan, with the loan amount, down payment, points and date this rate was accurate stated beside it.Regulation Z requires rates to be stated as an APR, and a bare teaser rate leaves the wrong impression.
Low payments of $1,450 a month.A payment example with the APR, the down payment and the full repayment terms shown right next to it.A payment amount is a trigger term, so the other disclosures have to appear in the same ad.
Totally free checking.Checking with no monthly maintenance fee, with every other fee listed on the account page.Regulation DD bars "free" if any maintenance or activity fee can apply.
You’re pre-approved! Call now.Start a pre-qualification and a loan officer will confirm what you may qualify for.Regulation N lists false preapproval claims as a prohibited misrepresentation.
A government home loan program for you.We offer FHA and VA loans, and we will explain which loan fits your situation.Implying government endorsement is barred unless the loan really is government-backed.
Grow your savings with our FDIC-insured investment accounts.Investment products are not FDIC-insured, are not deposits and may lose value.The FDIC statement must not appear on non-deposit products, and the non-deposit notice is required.
HOW WE RESEARCH YOUR INDUSTRY
Research first. Then a report you can actually read.
Month one is research, and you see the output of every step. After that, one plain-English report every month.
YOUR UX/SEO BLUEPRINT
How we get there
- 1We map your marketWho ranks for the loan needs and places you serve, what they say, and what an AI assistant answers when someone asks where to borrow.You get: A market map of your competitors and search demand
- 2We learn your borrowersLoan officer notes, reviews and the questions borrowers ask at application show how people describe their need. We write in their words.You get: Borrower-language notes that shape every page
- 3We check the rulesWe read the advertising, fair lending, RESPA and insurance rules that apply to your charter and states, and flag risks before anything is published. Your compliance officer has the final word.You get: A compliance checklist for your site, ads and loan officer material
- 4We write the BlueprintA UX and SEO Blueprint sets out the pages, structure, keywords, content and the order we build in, timed to your review cycle.You get: Your UX/SEO Blueprint
- 5We measure every monthOne report a month, in plain English, tied to application starts, funded loans and the next decision your growth manager recommends.You get: A monthly report and a clear next step
EVERY MONTH
Your monthly report
- 1What happenedApplication starts, appointments booked and accounts opened, by loan type and by source.
- 2What went liveEvery page, ad and post published this month, with dates, ready for your compliance records.
- 3What it meansA plain-English reading of the numbers, set against rate moves and your lending goals.
- 4What we recommendThe next step, and why it is right for this point in the rate cycle.
- 5What we need from youCompliance approvals, access and decisions, listed in order, so nothing waits.
OUR WORK
What we have done in banking, lending and mortgage
Delivered work for businesses in this industry. Full case studies, with the numbers behind them, are being written.
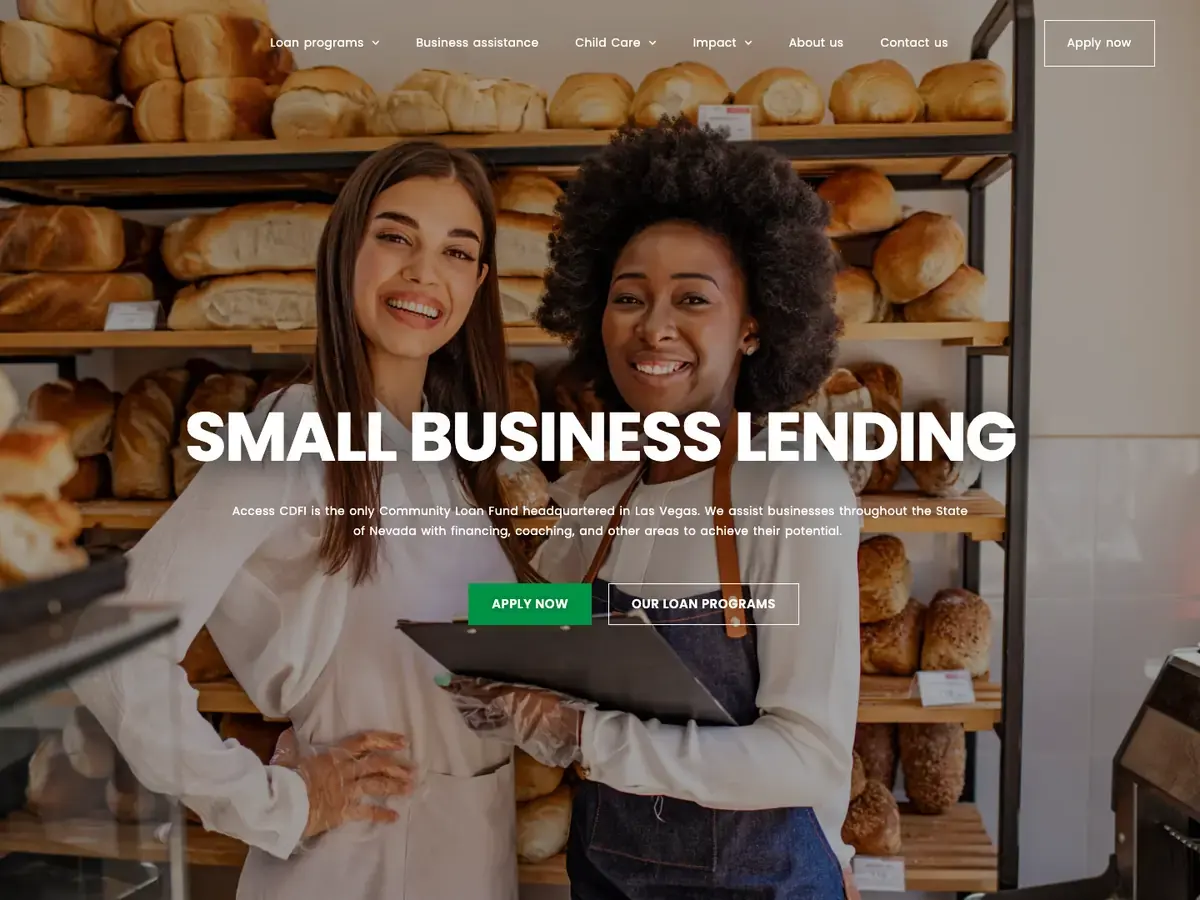
Access CDFI
Website design and build
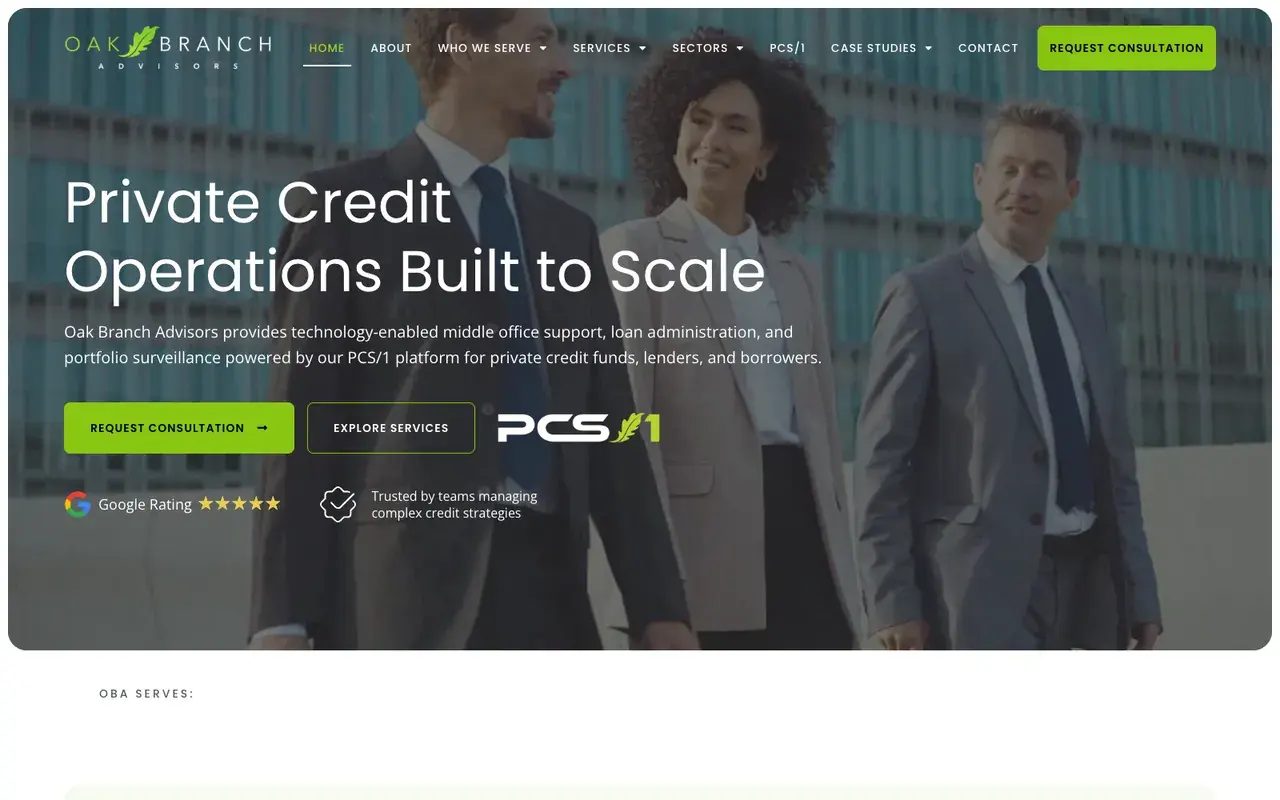
Oak Branch Advisors
Website redesign, SEO, AEO
YOUR TURN
Let us look at your banking, lending and mortgage’s site.
- Search basics
- AI answers
- Speed
- Trust signals
- What stops enquiries
LET’S TALK
Talk to a growth manager who knows advisors.
Book a call, or send us your site and a strategist will review it by hand. Either way, no obligation.
Book a call with a strategist
- 1We listenA one-to-one conversation about your lender, who you serve and what is getting in the way.
- 2We tell you honestlyWhether and how we can help, and what we would do first. No sales script.
- 3You decideNo obligation and no pressure. If it is not a fit, we will say so.
“Great support and experience from these guys. I was apprehensive about using a web developer, but they proved me wrong.”
“Extremely professional team-- very consultative on how to develop a modern web interface. Excellent support for design and graphics.”
“We are a small non-profit but Webtec design has treated us like a fortune 500 Company. Always responding promptly to any needs that may arise along with top notch customer service and sales.”
Questions lenders ask us.
What does a growth manager do for a bank, credit union or lender?
Your growth manager owns the plan for growing lending and deposits online. They review application starts, funded loans and accounts opened each month, and recommend what to do next. They bring in our specialists when you choose to buy the work. They also build compliance review time into every schedule. At the Advisor level they give direction rather than hands-on work. Many institutions start there.
Do you understand Regulation Z, Regulation DD and RESPA?
We research the rules that apply to you and build around them. That includes Regulation Z trigger terms, Truth in Savings yield rules, RESPA Section 8, fair lending, NMLS IDs and the FDIC or NCUA statements. We flag risks before anything goes live. We are not lawyers or compliance officers, so your compliance team has final sign-off on everything we write.
Can you work inside our compliance review process?
Yes. Your growth manager plans around your review cycle, and drafts arrive with disclosures, notices and NMLS IDs already in place. Every month you get a dated list of what went live to support your records. Final approval always stays with your compliance team.
Can you help our individual loan officers?
Yes, inside your brand and rules. We build a consistent loan officer page and profile template with NMLS IDs, licenses, loan types and a booking link, so every officer looks as trustworthy as the institution. Loan officers then share one approved set of material instead of making their own.
How much does it cost?
It depends on which services fit your institution, so we scope it after the free audit instead of guessing. We tell you the cost before you commit. For SEO we recommend six months because it takes time to compound, and we report every month.
Can you guarantee applications, funded loans or rankings?
No, and be wary of anyone who does. Search engines, AI assistants and rates change, and results also depend on your pricing, your reputation and how fast your team replies. We guarantee the work: a documented plan, a growth manager and project manager, monthly reporting and honest advice.
Do we have to buy every service?
No. Start with a growth manager, or with any single service, and add more when it makes sense. We would rather you buy the one thing that fits than a package you do not need. The free audit tells us where to begin.